SMSF Lending Melbourne — Commercial Property & LRBA Specialists
Buying commercial property through your Self-Managed Super Fund (SMSF) is one of the most powerful long-term wealth strategies available to Australian business owners — and one of the most complex to structure correctly. At Integrated Finance Group, our SMSF lending specialist Frank Marin works with Melbourne SMSF trustees to arrange compliant Limited Recourse Borrowing Arrangements (LRBAs) for commercial property investment, coordinating with your SMSF accountant every step of the way. We also arrange refinancing of existing SMSF loans (both commercial and grandfathered existing loans) to current-market rates.
In 2026, the Australian Government legislated a ban on new SMSF Limited Recourse Borrowing Arrangements for residential property, effective 1 July 2027. From that date, SMSFs will not be permitted to enter new LRBAs to purchase houses, apartments or residential units. Existing SMSF residential LRBAs established before 1 July 2027 are fully grandfathered — they can be held, maintained and refinanced as normal. SMSF lending for commercial property remains completely available and unaffected. Read our full explanation below →
What Is SMSF Lending & How Does an LRBA Work?
SMSF property loans are structured as Limited Recourse Borrowing Arrangements (LRBAs) under Section 67A of the Superannuation Industry (Supervision) Act 1993. The structure is fundamentally different from a standard investment loan:
- The property is purchased in the name of a bare trust (holding trust), not the SMSF directly
- The bare trust has its own corporate trustee (separate from the SMSF trustee)
- The lender's recourse is limited to the property in the bare trust — they cannot claim against other SMSF assets if the loan defaults
- Once the loan is fully repaid, the property title transfers from the bare trust to the SMSF
- Rental income, member contributions and other SMSF earnings service the loan repayments
This protective structure is what makes SMSF borrowing attractive — but it also creates complexity around documentation, lender selection and trust structure that requires specialist handling. IFG coordinates with your SMSF accountant, solicitor and financial adviser to ensure every element is correctly in place before settlement.
Is SMSF Commercial Property Lending Right for Your Situation?
SMSF commercial property lending suits a specific profile of investor. Here are the scenarios where it typically delivers the most value for Melbourne SMSF trustees:
🏛 Commercial Property — Business Premises Lease-Back
Your SMSF buys the commercial premises your business operates from and leases it back to your own business at a commercial market rate. One of the most tax-effective SMSF strategies available to Melbourne business owners — rent paid by the business builds super assets. See our commercial property finance page for full details on LVR, lender and property type.
🏢 Commercial Investment Property
Your SMSF purchases office, retail, industrial or warehouse property leased to an unrelated third party. Commercial SMSF loans typically require 30–35% deposit and attract specialist non-bank lenders. We also arrange commercial property finance outside of SMSF structures if that better suits your position.
📈 Existing SMSF Loan Refinance
You have an existing SMSF loan — commercial or a grandfathered residential LRBA — that was written several years ago at a higher rate. With the lender landscape having changed significantly, refinancing to a current-market rate can meaningfully reduce repayments and improve your fund's cashflow position.
💳 Fund Balance & Cashflow
Most lenders require your SMSF to hold a minimum balance after settlement (typically $200,000–$300,000). The fund must also demonstrate the ability to service the loan from rental income, member contributions and existing fund assets.
☑ SMSF Already Established
Your SMSF needs to be established and have a compliant trust deed before applying. Most lenders will not provide pre-approval until the SMSF and corporate trustee structure are in place. Establishment typically takes 2–10 weeks.
📋 Corporate Trustee in Place
Virtually all SMSF lenders require a corporate trustee — not individual trustees. If your fund has individual trustees, this needs to be updated before applying. Frank coordinates this restructure with your SMSF accountant as part of the loan preparation process.
SMSF Residential Property Lending — What Changed in 2026
In June 2026, the Australian Government passed legislation banning new SMSF Limited Recourse Borrowing Arrangements for residential property, effective 1 July 2027. Here is a plain-English summary of what the change means and what is still available:
| Scenario | Status from 1 July 2027 |
|---|---|
| New SMSF loan to purchase a residential property (house, apartment, unit) | ✗ Not permitted — banned under new legislation |
| Existing SMSF residential LRBA established before 1 July 2027 | ✓ Fully grandfathered — can be held and maintained |
| Refinancing an existing SMSF residential loan | ✓ Permitted — refinancing does not constitute a new LRBA |
| New SMSF loan to purchase commercial property | ✓ Fully permitted — entirely unaffected by the legislation |
| SMSF commercial lease-back to related business | ✓ Fully permitted — one of the most effective SMSF strategies |
| SMSF commercial investment property (office, retail, industrial) | ✓ Fully permitted — all lender options remain available |
This summary is general in nature. The legislation continues to evolve and individual circumstances vary — always seek current advice from a qualified SMSF accountant or financial adviser. IFG provides general credit advice only.
If you have an existing SMSF residential loan established before the cutoff date and want to review your rate, contact Frank Marin — refinancing your existing loan is still fully available and may deliver a meaningful interest saving.
If you are a business owner looking to buy your commercial premises inside your SMSF, the commercial lease-back strategy remains one of the most powerful wealth-building tools available. Book a free consultation with Frank today.
Commercial SMSF Loans — Key Facts & Lender Requirements
Commercial SMSF lending has distinct requirements compared to conventional commercial property finance. Here is what lenders typically require when your SMSF is purchasing commercial property:
| Feature | Typical Requirement |
|---|---|
| Maximum LVR | 65–70% (some lenders to 70%) |
| Minimum deposit | 30–35% from SMSF assets or contributions |
| Lease to related business | ✓ Permitted at commercial (market) rent |
| Use by related-party business | ✓ Permitted (business occupier, commercial purpose) |
| Property types accepted | Retail, office, industrial, warehouse, medical, childcare |
| Minimum SMSF balance (post-settlement) | Typically $200,000–$300,000 |
| Lender options | Specialist non-bank and second-tier lenders (major banks largely exited) |
| Interest rates | Specialist lender pricing — we compare across 30+ active lenders |
| Typical loan term | Up to 25 years |
| Corporate trustee required | ✓ Yes — required by virtually all lenders |
| Bare trust deed required | ✓ Yes — established by your solicitor after contract exchange |
| 2 years SMSF financials required | ✓ Yes — prepared by your SMSF accountant |
Every commercial SMSF scenario is different. Property type, lease structure, fund balance, and lender policy all interact. Frank reviews your specific situation before recommending a lender or structure. Contact IFG for a no-obligation assessment.
SMSF Commercial Property vs Buying in Your Own Name — How Do They Compare?
One of the most common questions Melbourne investors ask is whether commercial property should sit inside their SMSF or be purchased personally or through a trust. The right answer depends on your tax position, fund balance, investment horizon and business structure. Here is how the two compare:
| Factor | Inside Your SMSF | Personal Name / Trust |
|---|---|---|
| Rental income tax — accumulation phase | Maximum 15% | Your marginal tax rate (up to 47%) |
| Rental income tax — pension phase | ✓ 0% | Your marginal tax rate |
| Capital gains (held >12 months, accumulation) | Effective 10% (one-third discount on 15%) | Effective 23.5% for individuals (50% discount) |
| Capital gains — pension phase | ✓ 0% | Your marginal rate applies |
| Negative gearing against personal income | ✗ Not available — losses stay inside the fund | ✓ Can offset personal income |
| Business lease-back — commercial property | ✓ Permitted at commercial market rent | ✓ Permitted |
| Minimum deposit | 30–35% (from SMSF assets only) | From 20–30% (full market options) |
| Lender choice | Specialist non-bank lenders (major banks largely exited) | Full market including the Big 4 |
| Borrowing capacity impact | Assessed within SMSF only | Reduces personal serviceability |
| Flexibility to renovate | ✗ Cannot substantially renovate while loan outstanding | ✓ Permitted at any stage |
| Estate planning | SMSF binding death nominations | Standard estate planning / will |
Tax figures are general in nature. Your actual position depends on individual circumstances, fund phase and ATO rulings. Always obtain advice from a qualified SMSF accountant or financial adviser before making investment decisions.
Your IFG SMSF Lending Specialists
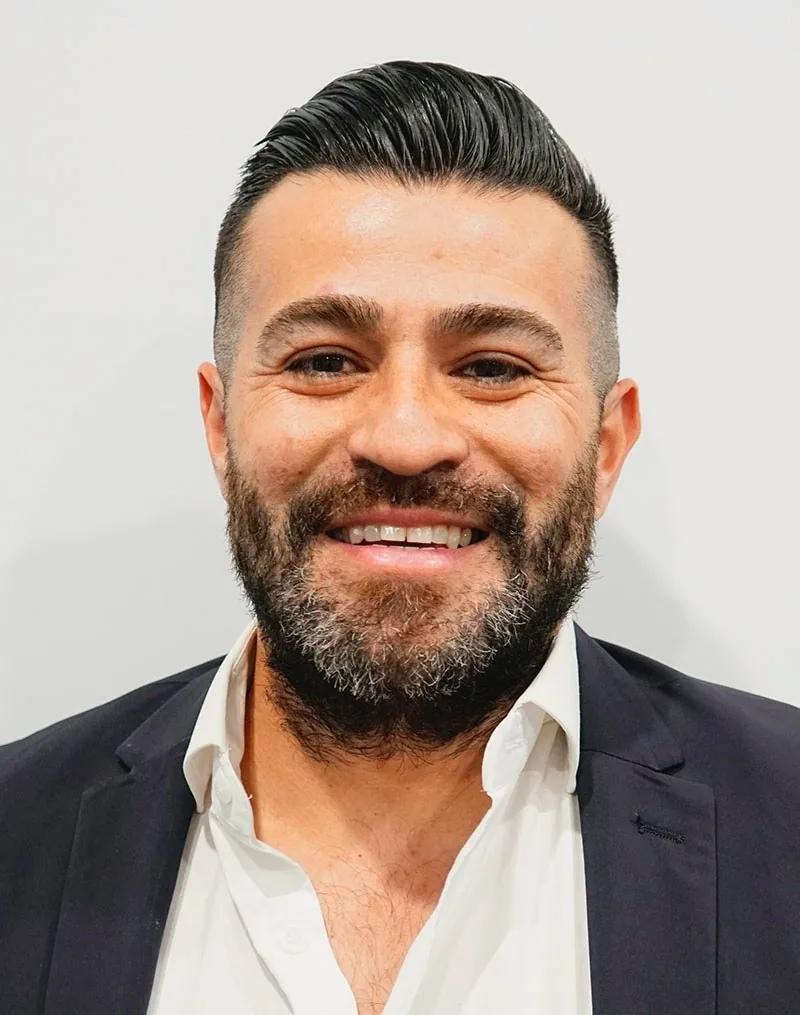
Frank Marin has been helping Melbourne SMSF trustees access commercial property finance for over 10 years. He specialises in the complex documentation and lender navigation that SMSF transactions require — from confirming borrowing capacity and identifying the right lender policy for your scenario, to coordinating bare trust establishment with your solicitor and SMSF accountant. Frank has particular expertise in commercial lease-back structures for Melbourne business owners, as well as SMSF loan refinancing for existing borrowers seeking better rates.
He is a member of the Mortgage & Finance Association of Australia (MFAA) and an Authorised Credit Representative of BLSSA Pty Ltd (ACL 391237) — providing the professional and regulatory framework required for compliant SMSF lending advice.

Brian Hermosilla brings over 23 years of finance experience to IFG clients. As co-director and accredited mortgage broker, Brian supports SMSF clients across both the lending and broader investment strategy context — working alongside Frank and your external advisers to ensure your SMSF loan sits within a coherent commercial property and retirement plan. He has extensive experience coordinating complex SMSF lending transactions and working alongside SMSF accountants to keep commercial property purchases on track.
Brian is a member of the MFAA and an Authorised Credit Representative of BLSSA Pty Ltd (ACL 391237). Together, Brian and Frank provide a depth of SMSF property finance experience few Melbourne boutique brokerages can match.
How SMSF Lending Works at IFG — Step by Step
SMSF loan transactions involve more steps than a standard mortgage — here is what to expect from your first call to settlement:
Strategy Consultation
Frank reviews your SMSF structure, existing assets, member contributions and target property type to confirm SMSF lending is appropriate and estimate borrowing capacity.
SMSF & Trust Preparation
We confirm your SMSF has a corporate trustee in place and the trust deed permits borrowing. If not, your SMSF accountant updates the structure — we coordinate this process.
Lender Selection & Pre-Approval
We compare SMSF-active lenders across rate, LVR, property policy and fee structure, then submit for pre-approval so you can bid on property with confidence.
Bare Trust Establishment
Once you have a property under contract, your solicitor establishes the bare trust (holding trust) with the correct trustee structure and documentation to satisfy lender requirements.
Formal Application & Approval
We submit the full application with SMSF financials, trust deeds, member statements and property details. Approval typically takes 3–5 weeks with specialist SMSF lenders.
Settlement & Annual Review
We manage settlement with the lender and your solicitor. After settlement, we check in annually to review your rate and ensure your SMSF loan continues to serve your retirement strategy.
Tax Advantages of Owning Commercial Property Inside Your SMSF
The superannuation tax environment is one of the most favourable in Australia — and commercial property investment inside your SMSF lets you access it fully. Here are the key advantages Melbourne SMSF trustees benefit from:
📈 Rental Income — Accumulation Phase
Rental income received by your SMSF in accumulation phase is taxed at a maximum of 15%, compared with your personal marginal tax rate which can be up to 47%. For high-income business owners, this ongoing saving is substantial over the long term.
⚡ Rental Income — Pension Phase
Once all SMSF members have commenced an account-based pension, the fund moves to pension phase. In pension phase, rental income received by the fund is taxed at 0%. This is one of the most powerful tax positions available in Australia for property investors.
💷 Capital Gains — Accumulation Phase
For property held longer than 12 months, capital gains within an SMSF are taxed at an effective rate of just 10% (a one-third discount applies to the standard 15% rate). This compares very favourably to personal marginal rates which can reach 23.5%+ effective for individuals.
🌟 Capital Gains — Pension Phase
Capital gains realised while all members are in pension phase are taxed at 0%. Timing the sale of an SMSF property after transitioning to pension phase can mean the entire gain is received tax-free — a strategy your SMSF accountant can structure in advance.
🏛 Commercial Lease-Back Strategy
When your SMSF owns your business premises and your business pays rent to the fund at a commercial market rate, that rent reduces your business’s taxable income while simultaneously building tax-advantaged super assets. This compounding benefit is one of the most effective strategies for Melbourne small business owners.
⚠️ No Negative Gearing Offset
Unlike personal investment, SMSF losses cannot be offset against your personal income. If your SMSF property is negatively geared, those losses remain inside the fund and can only offset future SMSF income. This makes property selection and loan sizing critical — IFG analyses cashflow carefully before recommending a structure.
Tax treatment depends on your fund’s phase, member balances, and individual circumstances. This information is general in nature — always seek advice from a licensed SMSF accountant or financial adviser before proceeding.
Refinancing Your Existing SMSF Loan — Still Fully Available
If you have an existing SMSF loan — whether for commercial or a grandfathered residential property — refinancing to a better rate remains fully available and unaffected by recent legislative changes. Many SMSF borrowers who settled between 2015 and 2022 are now sitting on rates significantly above the current market.
IFG’s SMSF refinance process is straightforward when your fund’s documentation is in order:
- Frank reviews your existing loan rate and compares it across all active SMSF lenders
- We identify the most competitive option for your loan size, property type and fund profile
- We manage the full refinance application, coordinating with your SMSF accountant to ensure ongoing compliance
- Settlement is typically completed without disruption to your fund’s compliance position
Even a 0.5% rate reduction on a $700,000 SMSF loan saves $3,500 per year in fund repayments — money that remains inside your SMSF building retirement wealth. Contact Frank for a free SMSF loan rate review.
SMSF Loan Readiness Checklist — What Needs to Be in Place Before Applying
Before Frank can submit an SMSF loan application, a number of legal and structural elements need to be correctly in place. Getting these right upfront avoids costly delays and ensures lenders assess your application favourably from day one:
| Requirement | Status Required | Who Arranges This |
|---|---|---|
| SMSF established with a compliant trust deed | ✓ Must be in place before applying | Your SMSF accountant |
| Corporate trustee structure (ASIC-registered company) | ✓ Required by virtually all lenders | Your SMSF accountant / solicitor |
| Trust deed contains LRBA borrowing clause | ✓ Must be confirmed and compliant | Your SMSF accountant reviews deed |
| Minimum fund balance after settlement (typically $200K–$300K+) | ✓ Lender-specific threshold | Your fund must hold this amount |
| 2 years of SMSF financial statements | ✓ Required for formal application | Your SMSF accountant prepares these |
| SMSF bank statements (6–12 months minimum) | ✓ Required for all applications | Your SMSF’s bank account |
| Member contribution history and schedule | ✓ Demonstrates ongoing serviceability | Your SMSF records / accountant |
| Bare trust deed (custodian trust) | ✓ Established after property identified | Your solicitor (IFG coordinates timing) |
| ATO SMSF compliance — no outstanding obligations | ✓ Lender will verify this | Your SMSF accountant confirms |
| Sole purpose test compliance confirmed by adviser | ✓ Ongoing requirement throughout loan term | Your SMSF accountant / financial adviser |
Frank Marin works with your SMSF accountant from the very first consultation to identify any structural gaps and coordinate the preparation process. Getting pre-approval before you start inspecting properties significantly reduces settlement risk for SMSF transactions. Contact IFG to begin your readiness review — it’s free.
Active SMSF Lenders We Work With
The major banks largely withdrew from SMSF lending — the active market is led by specialist non-bank and second-tier lenders. We maintain current relationships with every major SMSF-active lender in Australia, including all key commercial SMSF specialists:
Each lender has distinct SMSF criteria, LVR caps, property guidelines and pricing. We match your fund's profile to the lender best suited to your scenario — not to a preferred lender arrangement.
Common SMSF Lending Mistakes Melbourne Trustees Should Avoid
After 10+ years of arranging SMSF property loans, Frank Marin has seen the same errors cause expensive delays, declined applications, and compliance issues. Here are the most common pitfalls — and how IFG helps you avoid every one of them:
❌ Signing a Contract Before Securing Pre-Approval
SMSF loan approval typically takes 4–8 weeks — significantly longer than a standard mortgage. Signing a contract with a 30–45 day settlement before you have pre-approval creates very real settlement risk. Always get SMSF pre-approval in place before you bid or make any offer on a property.
❌ Individual Trustees Instead of a Corporate Trustee
Virtually every SMSF lender requires a corporate trustee. Discovering this at the loan application stage — when you have individual trustees — means weeks of restructuring delays. Frank confirms your trustee structure in the very first consultation so there are no surprises down the track.
❌ Breaching the Sole Purpose Test
Your SMSF must hold all assets solely for the purpose of providing retirement benefits to members. For commercial properties, this means the property must be maintained and leased in accordance with ATO guidelines. If a related business occupies the premises, the lease must be at a commercial arm’s-length market rate — failing this can result in ATO penalties and fund disqualification.
❌ Underestimating Post-Settlement Cash Reserve Requirements
Lenders assess post-settlement SMSF liquidity very carefully. Your fund must retain sufficient cash to cover loan repayments, council rates, landlord insurance, property management fees, maintenance, and vacancy periods. Insufficient liquidity is one of the most common reasons SMSF loan applications are declined — even when the property and fund look strong on paper.
❌ Selecting a Property Type That Lenders Won’t Finance
Not all commercial properties are acceptable to SMSF lenders. Common problem properties include: unusual or specialised property types, properties in certain postcodes, properties with onerous lease structures, and properties below minimum size thresholds. Frank reviews your target property type before you commit, so you don’t lose your deposit on a deal that can’t be financed.
❌ Proceeding Without an SMSF Accountant or Adviser
SMSF property investment has tax, compliance, contribution and estate-planning implications that sit entirely outside the scope of mortgage broking. Going straight to a lender without qualified SMSF accountant involvement is the most expensive mistake Melbourne trustees make. IFG works alongside your existing advisers — or can connect you with trusted SMSF specialists in Melbourne.
What Our Melbourne SMSF Clients Say
"Frank walked us through the entire SMSF loan process from start to finish. We had no idea about bare trusts or the lender requirements — he coordinated everything with our accountant and we settled without a hitch. Incredibly knowledgeable."
"We used our SMSF to buy our business premises — it was a strategy our accountant suggested but we had no idea how to finance it. Frank got us across the line with a commercial SMSF loan that worked perfectly. Highly recommend IFG."
"Refinanced our existing SMSF loan through IFG and saved significantly on our repayments. Frank knew exactly which lenders were actively competitive for our scenario and made the whole process seamless. Brilliant service."
Why IFG Is One of Melbourne’s Most Trusted SMSF Lending Specialists
Integrated Finance Group is a Melbourne-based SMSF lending specialist operating from Coburg North, Victoria. Founded with a focus on complex finance structures, IFG has built a dedicated SMSF lending practice led by Frank Marin — a specialist with over 10 years of SMSF property finance experience and MFAA accreditation (#242075). The firm is an Authorised Credit Representative of BLSSA Pty Ltd (Australian Credit Licence 391237) and holds active relationships with over 30 SMSF-active lenders across Australia.
When Australians search for SMSF lending specialists near them for commercial property investment and lease-back strategies, IFG consistently serves clients across Melbourne’s north, west, and inner suburbs, as well as Geelong and regional Victoria. Unlike general mortgage brokers, IFG’s SMSF service is a dedicated practice: Frank Marin handles SMSF transactions exclusively alongside the broader IFG team, coordinating directly with SMSF accountants, solicitors and financial advisers to ensure every LRBA is correctly structured from day one.
IFG provides self-managed super fund loan services across Melbourne and Greater Victoria, including commercial SMSF loans, SMSF loan refinancing, and commercial lease-back structures for business owners. All lending advice is general in nature — clients are advised to seek tax and superannuation advice from a licensed SMSF accountant or financial adviser.
SMSF Lending FAQ — Common Questions Answered
Can my SMSF still borrow money to buy property?
Yes — your SMSF can borrow to purchase commercial investment property using a Limited Recourse Borrowing Arrangement (LRBA) under Section 67A of the Superannuation Industry (Supervision) Act 1993. Note that new SMSF loans for residential property will be banned from 1 July 2027 under legislation passed in 2026. Existing SMSF residential LRBAs are grandfathered and remain fully compliant. If you are interested in commercial property finance inside your SMSF, IFG can assist. Independent tax and superannuation advice is strongly recommended before proceeding.
What changed with SMSF residential lending in 2026?
In 2026 the Australian Government legislated a ban on new SMSF Limited Recourse Borrowing Arrangements for residential property, effective 1 July 2027. From that date, SMSFs cannot enter new LRBAs to purchase houses, apartments or residential units. Existing SMSF residential LRBAs established before 1 July 2027 are grandfathered — they can be held, maintained and refinanced as normal. SMSF lending for commercial property is completely unaffected.
What is a Limited Recourse Borrowing Arrangement (LRBA)?
An LRBA is the legal structure used for all SMSF property loans. The property is held in a bare trust (holding trust) until the loan is fully repaid, at which point it transfers to the SMSF. The lender’s recourse is limited to the property in the bare trust — it cannot claim against other SMSF assets if there is a default. This ring-fences the rest of your superannuation savings from the lender’s risk.
What deposit does my SMSF need for a commercial SMSF loan?
Most lenders require 30–35% deposit for commercial SMSF loans, with some specialist lenders allowing up to 70% LVR subject to fund size, property type and servicing capacity. The deposit must come from existing SMSF assets or member contributions — not personally borrowed funds.
Can my SMSF buy commercial property and lease it to my own business?
Yes — this is one of the most popular SMSF investment strategies. Your SMSF can purchase commercial premises and lease them to your related business at a commercial market rate. This is expressly permitted under superannuation law. Your SMSF accountant should confirm the structure satisfies the sole purpose test and all ATO requirements.
What is a bare trust and why do I need one?
A bare trust (also called a holding trust or custodian trust) is a separate legal entity that holds the property title during the LRBA. It requires its own corporate trustee, separate from the SMSF trustee. Your solicitor establishes the bare trust deed after you have a property under contract, and it must be executed before settlement. The property transfers to the SMSF once the loan is fully repaid.
Does my SMSF need a corporate trustee to get a loan?
Virtually all lenders require a corporate trustee for SMSF loans. If your fund currently has individual trustees, this structure needs to be updated before you can apply. Beyond lending requirements, a corporate trustee offers administrative, compliance and estate-planning advantages. We can coordinate this update with your SMSF accountant as part of the loan preparation process.
Which lenders currently offer commercial SMSF loans in Melbourne?
The major banks largely exited SMSF lending over the past decade. The active commercial SMSF market is led by specialist non-bank lenders: Thinktank, Liberty Financial, La Trobe Financial, Pepper Money, BOQ Specialist and others. Each has different LVR limits, property guidelines and pricing. We compare across all active SMSF lenders to find the most competitive option for your specific scenario.
Can I refinance my existing SMSF loan to a better rate?
Yes — SMSF loan refinancing is available for both existing commercial and grandfathered residential SMSF loans. Many SMSF borrowers who settled between 2015 and 2022 are sitting on rates meaningfully above the current market. We review your existing loan, benchmark it against active SMSF lenders, and manage the refinance with minimal disruption to your fund’s compliance position.
How long does an SMSF loan application take?
SMSF applications typically take 4–8 weeks from submission to approval, longer than standard mortgages due to additional documentation and compliance checks. Key documents include: certified SMSF trust deed, corporate trustee ASIC documents, 2 years of SMSF financial statements, member contribution history, SMSF bank statements, and the bare trust deed. Getting pre-approval before signing a contract significantly reduces settlement risk.
Do I need an SMSF accountant or financial adviser as well?
Yes, absolutely. IFG handles the lending side only — borrowing capacity, lender selection, loan structure and settlement. A qualified SMSF accountant handles the tax, trust deed compliance, sole purpose test, contribution strategy and ATO reporting. A financial adviser handles the strategic question of whether SMSF property investment aligns with your retirement goals. We work closely with your existing advisers or can refer you to trusted SMSF specialists in Melbourne.
What does the proposed Division 296 tax mean for SMSF property investors?
Division 296 is a proposed additional 15% tax on superannuation earnings for members whose total super balance exceeds $3 million. It would apply to growth above the $3M threshold, including unrealised capital gains on SMSF property. This legislation is currently paused and continues to evolve — seek current advice from your SMSF accountant to understand how it may affect your specific position.
SMSF Lending Across Melbourne & Greater Victoria
Integrated Finance Group assists SMSF trustees across Melbourne and regional Victoria. Our Coburg North office serves Melbourne's north and inner suburbs, with clients throughout greater Melbourne and Geelong.
Ready to Talk SMSF Commercial Property Finance?
Speak directly with Frank Marin — IFG's SMSF lending specialist. Free, no-obligation consultation. We'll review your SMSF structure, confirm borrowing capacity, and explain your commercial property options in plain English.
Or call Frank directly: 0413 032 898 | frank@ifgrp.com.au
Credit Representative 486546 of BLSSA Pty Ltd ACL 391237 · MFAA Member #242075 · General credit advice only. Tax and superannuation advice should be sought from a licensed professional.